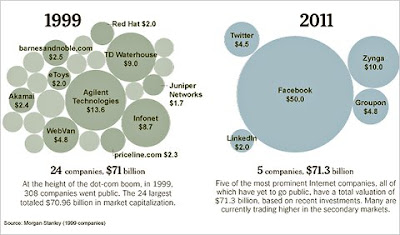
The state of U.S. manufacturing
Labels: economy, technology
"Copia" is Latin for "abundance," and this blog explores my belief that abundance is all around us. We live in a world of infinite possibilities,
and we have the ability to choose our own paths.
I write about a wide range of topics, and common themes are politics, civil liberties, health, the environment, and science.
Who am I? I'm Torq Anvil...
Labels: economy, technology
The median starting salary for students graduating from four-year colleges in 2009 and 2010 was $27,000, down from $30,000 for those who entered the work force in 2006 to 2008, according to a study released on Wednesday by the John J. Heldrich Center for Workforce Development at Rutgers University. That is a decline of 10 percent, even before taking inflation into account.
Of course, these are the lucky ones — the graduates who found a job. Among the members of the class of 2010, just 56 percent had held at least one job by this spring, when the survey was conducted. That compares with 90 percent of graduates from the classes of 2006 and 2007.
Labels: economy
The rule of law and political accountability are desirable in their own right. Sometimes, they can get in the way of good, effective government, as when an Indian state is unable to make a decision on a major infrastructure project due to litigation and public protests, or when the U.S. Congress cannot bring itself to deal with pressing problems like entitlements due to the influence of lobbyists and interest groups.From what I've read so far, it's clear to me that we're in a period of "political decay." I think we could use a good psychohistorian right now...
But at other times rule of law and accountability are necessary to preserve good government. Under the right conditions, a strong authoritarian system can produce extremely effective government. Political systems need to be able to endure changing external conditions and changing leaders. The checks on state authority provided by rule of law and accountability serve to reduce the variance in governmental performance: they constrain the best governments, but they also prevent bad ones from spiraling out of control.
Labels: biology, economy, foreign policy, history, quotes, U.S. politics
More here.
Labels: economy, U.S. politics
For bin Laden ... success was not to be measured in body counts. It was to be measured in deficits, in borrowing costs, in investments we weren’t able to make in our country’s continued economic strength. And by those measures, bin Laden landed a lot of blows.
Nobel laureate Joseph Stiglitz estimates that the price tag on the Iraq War alone will surpass $3 trillion. Afghanistan likely amounts to another trillion or two. Add in the build-up in homeland security spending since 9/11 and you’re looking at yet another trillion. And don’t forget the indirect costs of all this turmoil: The Federal Reserve, worried about a fear-induced recession, slashed interest rates after the attack on the World Trade Center, and then kept them low to combat skyrocketing oil prices, a byproduct of the war in Iraq. That decade of loose monetary policy may well have contributed to the credit bubble that crashed the economy in 2007 and 2008.
Then there’s the post-9/11 slowdown in the economy, the time wasted in airports, the foregone returns on investments we didn’t make, the rise in oil prices as a result of the Iraq War, the cost of rebuilding Ground Zero, health care for the first responders and much, much more.
Labels: economy, national security, U.S. politics
Labels: economy, energy, U.S. politics
Labels: economy, U.S. politics
There’s nothing serious about a plan that claims to reduce the deficit by spending a trillion dollars on tax cuts for millionaires and billionaires. And I don't think there’s anything courageous about asking for sacrifice from those who can least afford it and don’t have any clout on Capitol Hill. That's not a vision of the America I know.The President spends some time filling in the picture of how we got into our current situation and reminds us how we've dealt with similar problems in the past. And he forcefully states that he will neither allow Medicare to be dismantled on his watch nor sign off on continuing the Bush tax cuts for the wealthiest one percent of Americans beyond 2012 when they're set to expire.
Labels: economy, quotes, U.S. politics, video
In my sociology class in Las Vegas, we discussed how ridiculously low the official poverty line is in America. A single person is considered to be living below the poverty line if they are making less than roughly $10,000/year.And I don't know how President Obama can justify it when General Electric pays no taxes, but I find it scandalous that GE's CEO Jeff Immelt heads Obama's Council on Jobs and Competitiveness.
This [New York Times] article looks at how much people really need to make in order to have a minimum level of economic survey (their figure is closer to $30,000/year for a single person).
Now consider the fact that the most recent statistics show that about 14% of Americans live below the "official" poverty line. Meanwhile, the top one percent hold forty percent of the country's wealth.
Labels: climate change, economy, energy, Las Vegas, national security, U.S. politics
Labels: economy, history, U.S. politics, video
No matter how much Obama talks about his “tough” new financial regulatory reforms or offers rote condemnations of Wall Street greed, few believe there’s been real change. That’s not just because so many have lost their jobs, their savings and their homes. It’s also because so many know that the loftiest perpetrators of this national devastation got get-out-of-jail-free cards, that too-big-to-fail banks have grown bigger and that the rich are still the only Americans getting richer.I hadn't heard of it before reading Rich's column, but now I have to see the new documentary, Inside Job, about the financial meltdown:
Asked in “Inside Job” why there’s been no systematic investigation of the 2008 crash, Roubini answers: “Because then you’d find the culprits.” With the aid of the “Manhattan Madam” (and current stunt New York gubernatorial candidate) Kristin Davis, the film also asks why federal prosecutors who were “perfectly happy to use Eliot Spitzer’s personal vices to force him to resign in 2008” have not used rampant sex-and-drug trade on Wall Street as a tool for flipping witnesses to pursue the culprits behind the financial crimes that devastated the nation.Oligarchy.
The Obama administration seems not to have a prosecutorial gene. It’s shy about calling a fraud a fraud when it occurs in high finance. This caution was exemplified most recently by the secretary of housing and urban development, Shaun Donovan, whose response to the public outcry over the banks’ foreclosure shenanigans was to take to The Huffington Post last weekend. “The notion that many of the very same institutions that helped cause this housing crisis may well be making it worse is not only frustrating — it’s shameful,” he wrote.
Well, yes! Obama couldn’t have said it more eloquently himself. But with all due respect to Secretary Donovan’s blogging finesse, he wasn’t promising action. He was just stroking the liberal base while the administration once again punted. In our new banking scandal, as in those before it, attorneys general in the states, where many pension funds were decimated by Wall Street Ponzi schemes, are pursuing the crimes Washington has not. The largest bill of reparations paid out by Bank of America for Countrywide’s deceptive mortgage practices — $8.4 billion — was to settle a suit by 11 state attorneys general on the warpath.
Since Obama has neither aggressively pursued the crash’s con men nor compellingly explained how they gamed the system, he sometimes looks as if he’s fronting for the industry even if he’s not. Voters are not only failing to give the White House credit for its economic successes but finding it guilty of transgressions it didn’t commit. The opposition is more than happy to pump up that confusion. When Mitch McConnell appeared on ABC’s “This Week” last month, he typically railed against the “extreme” government of “the last year and a half,” citing its takeover of banks as his first example. That this was utter fiction — the takeover took place two years ago, before Obama was president, with McConnell voting for it — went unchallenged by his questioner, Christiane Amanpour, and probably by many viewers inured to this big lie.
Labels: economy, movies, U.S. politics
Labels: economy, Iraq, national security, video
This White House has "vilified industries," complains the U.S. Chamber of Commerce. America is burdened with "an anti-business president," moans the Weekly Standard.And this:
Would that all presidents were this anti-business: According to the St. Louis Federal Reserve, corporate profits hit $1.37 trillion in the first quarter -- an all-time high. Businesses are sitting on about $2 trillion in cash reserves. Business spending jumped 20 percent last quarter and is up by 13 percent against 2009. And the Obama administration has cut taxes for small businesses and big ones alike. Maybe the president could be anti-me for a while. I could use the money.
The reality is that America's supposedly anti-business president has led an extremely pro-business recovery. The corporate community has recovered first, and best. The populist tone that conservative magazines and business groups decry is partly in reaction to this: As corporate America's position is getting better and better, the recovery is looking shakier and shakier. Unemployment is high. Housing looks perilously close to a double dip. Job growth is weak. Businesses aren't hiring. The 71,000 jobs the private sector added in July aren't sufficient to keep up with population growth, much less cut into the ranks of the unemployed.
That is the catch-22 of the recovery: Businesses will start hiring when the economy recovers. And the economy will start to recover when businesses start hiring.
Not all recessions are created equal. Recessions caused by financial crises take a lot longer to dig out of than their more common cousins. One is like the flu. The other, a car crash. When the flu goes away, you're good. When a collision spins to a stop, that's when the long, slow process of healing begins.
In "This Time is Different: Eight Centuries of Financial Folly," Carmen Reinhart and Kenneth Rogoff study every financial crisis of the past 800 years. It's an exhaustive study, and its conclusions are depressing for a country that believes itself exceptional even in its suffering: We're not special.
If you consider unemployment, housing prices, government debt and the stock market, Rogoff says, "the U.S. is just driving down the tracks of a typical post-WWII deep financial crisis." In some areas, we're even a bit ahead of the game: Economic output usually falls by 9 percent. We held the drop to 4 percent.
Even the unevenness of our recovery is predictable. "Housing and employment come back much slower than equity and gross domestic product," Reinhart says. GDP usually falls for two years and then recovers. Equity can move even faster, which helps explain corporate America's rapid revival. But employment tends to fall for five years. And housing? That's usually a six-year slide.
Labels: economy, history, U.S. politics
But as expectations for the recovery diminish daily and joblessness shows no sign of easing — as the jobs report on Friday showed — a different view is taking hold. And with it, comes implications for policymaking.And not surprisingly (or surprisingly, depending on your level of cynicism), Americans are adapting and re-discovering that what they spend their money on may bring them more happiness than how much of it they spend:
The “new normal,” as it has come to be called on Wall Street, academia and CNBC, envisions an economy in which growth is too slow to bring down the unemployment rate, while the government is forced to intervene ever more forcefully in a struggling private sector. Stocks and bonds yield paltry returns, with better opportunities available for investors overseas.
If that sounds like the last three years, it should. Bill Gross and Mohamed El-Erian, who run the world’s largest bond fund, Pimco, and coined the phrase in this context, think the new normal has already begun and will last at least another three to five years.
On the bright side, the practices that consumers have adopted in response to the economic crisis ultimately could — as a raft of new research suggests — make them happier. New studies of consumption and happiness show, for instance, that people are happier when they spend money on experiences instead of material objects, when they relish what they plan to buy long before they buy it, and when they stop trying to outdo the Joneses.This was a interesting article, well worth a read.
If consumers end up sticking with their newfound spending habits, some tactics that retailers and marketers began deploying during the recession could become lasting business strategies. Among those strategies are proffering merchandise that makes being at home more entertaining and trying to make consumers feel special by giving them access to exclusive events and more personal customer service.
While the current round of stinginess may simply be a response to the economic downturn, some analysts say consumers may also be permanently adjusting their spending based on what they’ve discovered about what truly makes them happy or fulfilled.
Labels: being human, economy, U.S. politics
There’s a class war coming to the world of government pensions.With deep cuts being made in public services across the country, it's hard for me to disagree with the notion that government employees have to share some of the burden. And I liked this point in today's article, offered as advice to retirees with government pensions who might be thinking about suing over potential changes to their benefits:
The haves are retirees who were once state or municipal workers. Their seemingly guaranteed and ever-escalating monthly pension benefits are breaking budgets nationwide.
The have-nots are taxpayers who don’t have generous pensions. Their 401(k)s or individual retirement accounts have taken a real beating in recent years and are not guaranteed. And soon, many of those people will be paying higher taxes or getting fewer state services as their states put more money aside to cover those pension checks.
At stake is at least $1 trillion. That’s trillion, with a “t,” as in titanic and terrifying.
And if you’re a government retiree or getting close to the end of your career? Consider what it means to be a citizen in a community. And what it means to be civil instead of litigious, coming to the table and making a compromise before politicians shove it down your throat and you feel compelled to challenge them to a courthouse brawl.We can either realize that we're all in this together, and act accordingly, or fight endless "me first" battles which ultimately no one will win.
Labels: economy, U.S. politics
-- Stephen Colbert
| The Colbert Report | Mon - Thurs 11:30pm / 10:30c | |||
| Consumer Protection Agency - Barney Frank | ||||
| ||||
Labels: economy, U.S. politics, video
The growth of the American Oligarchy has been building for decades, and we've been its enablers.
When I was a boy in Brooklyn we shopped at Jack's Delicatessen. Jack was someone we knew and liked. When we ran short of money, Jack let us buy groceries "on the tab." He knew us. He trusted us to pay that tab. Most of us were good for it. Jack lived where we lived. He was our neighbor. Money spent at Jack's stayed in the neighborhood, and Jack and his kind had a stake in keeping our streets as decent as possible.
Then a shiny big supermarket came to the neighborhood with a bigger variety of products that cost less. Not much less. A nickel, a quarter. We didn't know who owned the supermarket, and we didn't ask. They didn't run tabs like Jack did, but it was all so shiny, and it was a little cheaper. We abandoned Jack, who'd been our friend. To save nickels and quarters, we abandoned him. Oh, we still went to Jack's, but not as often. Small businesses have slim profit margins. If customers come in "not as often," there goes the profit margin. There goes Jack. Now our money leaves the neighborhood. There goes the neighborhood. We "saved" our way out of the possibility of community.
By the 1990s, Wal-Mart was doing that to whole towns. Barnes & Noble and Borders did that to independent bookstores. Whole Foods did that to small health-food stores. Chains like McDonald's and Starbucks did that to Joe's Diner and Sally's Breakfast Nook. (Starbucks didn't even have to sell cheaply; it merely had to be convenient.) Detroit automakers invented "warranties" to have your car serviced at their outlets; indy garages went broke. Agribusiness did it to family farms. And each time we buy an item online when it's available at a local store, we're doing it all over again.
With every local business we abandoned, with every dime or dollar we saved, we bought into a system that had no need of community. No need of us, except purely as consumers. Once that system was established, we had nowhere else to go. We still need what we need, but when we buy it our money is siphoned to a capital-"E" Elsewhere that, over time, became capital-"O" Oligarchy. With globalization, the biggest firms not only no longer needed our communities, they no longer needed our country.
So while it would be easier to a) not read any of this, b) dismiss it out of hand, or c) attempt to rip it to shreds, you might then wonder, isn't that how we got into this situation? If you're not happy about how things are, would it be worth your time to consider another point of view?
I'm reminded of the great sociology course I took in Las Vegas with Jane Heenan in 2008. Every one of us walked into that classroom with the belief that we saw our world pretty clearly. I'm pretty damned sure we all left at the end of the term with a new perspective on what might really be going on. But to get from here to there, we had to be willing to give up some of our certainty about the assumptions we'd been living with.
The point is not to read this and simply agree with it. The point it to think and ask questions. As Ventura notes in the first of these columns, quoting Thomas Pynchon from Gravity's Rainbow, "If they can get you asking the wrong questions, they don't have to worry about the answers."
Here are links to the whole series:Labels: economy, history, quotes, U.S. politics

Coal is the world’s fastest growing fossil fuel (for the 8th year now) and likely will be for the next 10-20 at least. According to BP’s 2010 Statistical Review of World Energy released this month, coal now occupies a greater share of the world’s energy mix than at any point since 1970.I've been meaning to post about this article for over a month now, particularly because just three days later a piece was published in the New York Times Magazine about the imminent demise of the bluefin tuna:
This doesn’t receive much attention in the U.S. because our coal market is essentially disconnected from global markets and the domestic trend is quite the opposite. But there is a reason my colleague calls the global energy era we are embarking upon the “renaissance of coal.” China, India, Indonesia, Korea, Taiwan, Malaysia, and most of the rest of Asia are predicating their growth on coal....
In my view climate regimes that don’t address the coal issue — via addressing mitigation in developing world power sectors at a much larger scale than Kyoto ever accomplished — don’t have much hope from a mitigation perspective. And that is going to be really, really hard. Thus the game is looking more and more like adaptation. As we can see in China and India, they view development of a coal-based electricity infrastructure as essential to economic development.
What was in the water that day was a congregation of Atlantic bluefin tuna, a fish that when prepared as sushi is one of the most valuable forms of seafood in the world. It’s also a fish that regularly journeys between America and Europe and whose two populations, or “stocks,” have both been catastrophically overexploited. The BP oil spill in the Gulf of Mexico, one of only two known Atlantic bluefin spawning grounds, has only intensified the crisis. By some estimates, there may be only 9,000 of the most ecologically vital megabreeders left in the fish’s North American stock, enough for the entire population of New York to have a final bite (or two) of high-grade otoro sushi. The Mediterranean stock of bluefin, historically a larger population than the North American one, has declined drastically as well. Indeed, most Mediterranean bluefin fishing consists of netting or “seining” young wild fish for “outgrowing” on tuna “ranches.”An inability of the world's fishing nations to agree on limits that would ensure the sustainability of the remaining bluefin stocks may mean the loss of a truly unique animal:
There are two reasons that a mere fish should have inspired such a high-strung confrontation reminiscent of Greenpeace’s early days as a defender of whales. The first stems from fish enthusiasts who have for many years recognized the particular qualities of bluefin tuna — qualities that were they land-based creatures would establish them indisputably as “wildlife” and not just another “seafood” we eat without remorse. Not only is the bluefin’s dense, distinctly beefy musculature supremely appropriate for traversing the ocean’s breadth, but the animal also has attributes that make its evolutionary appearance seem almost deus ex machina, or rather machina ex deo — a machine from God. How else could a fish develop a sextantlike “pineal window” in the top of its head that scientists say enables it to navigate over thousands of miles? How else could a fish develop a propulsion system whereby a whip-thin crescent tail vibrates at fantastic speeds, shooting the bluefin forward at speeds that can reach 40 miles an hour? And how else would a fish appear within a mostly coldblooded phylum that can use its metabolic heat to raise its body temperature far above that of the surrounding water, allowing it to traverse the frigid seas of the subarctic?This may be our future. One where coal wins and the bluefin loses.
Yes, bluefin tuna are warmblooded.
Labels: biology, climate change, economy, environment, wildlife